Celebrating 25 Years

Keller Augusta Quarterly Q&A: Q3 with Lauren Hodgetts
Oct 7, 2026
Deal activity is slowly but steadily returning to commercial real estate as we progress through the second half of 2026. Keller Augusta Senior Director Lauren Hodgetts is seeing how rising rates, a crowded lending market, and evolving attitudes toward AI are shaping hiring across capital markets and development platforms. Keller Augusta can help you accomplish your hiring goals. Get in touch today.
Commercial real estate is heading into the final stretch of 2026 on relatively stable ground compared to the last few years, even if it's not the hyper-active market of the zero-interest-rate era.
The market widely expected the Federal Reserve's September rate increase, and while it’s too early to know how rate hikes will shape investment and lending strategy going forward, broader hiring trends have held. Over the past 18 months, recruitment activity for acquisitions, development, originations, and asset management talent has returned, with demand focused on senior-level professionals who can drive business activity.
The capital markets picture is more complicated. Private credit raised enormous sums of money to fill gaps left by the banks, then banks returned to lending, and the result is an extremely competitive debt landscape. Hiring is selective, a platform-by-platform story.
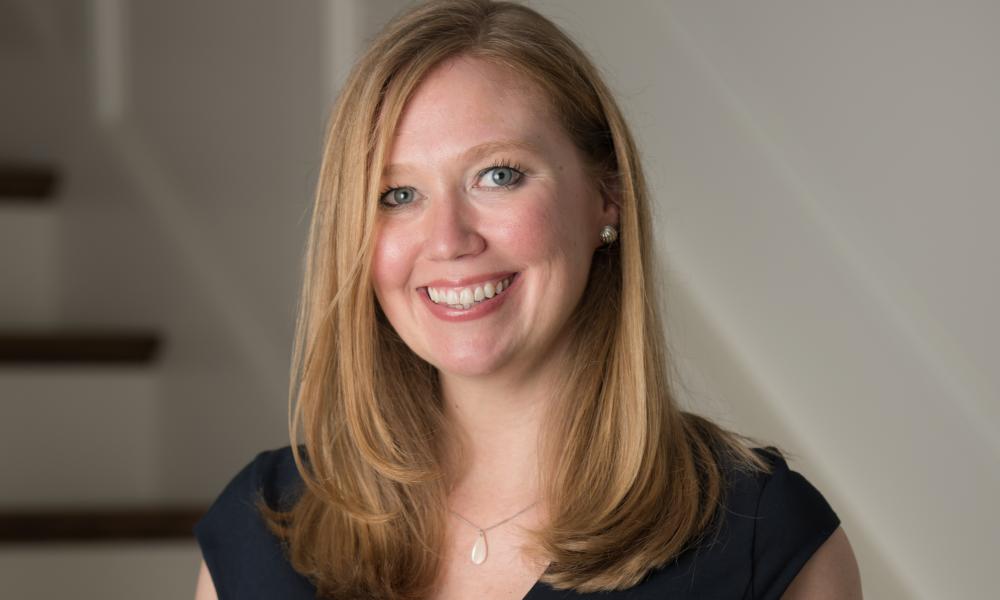
Keller Augusta Senior Director Lauren Hodgetts’ recruitment background is rooted in executive searches and commercial real estate capital markets and investment sales. Based in the firm’s New York office, she’s actively recruiting nationwide for platforms across development, investment, asset management, equity, and debt roles. Below, she discusses the trends she's seeing.ing.
Tell us about your role at Keller Augusta and the sectors and clients you focus on.
I've been with Keller Augusta for almost eight years, and I don't fall neatly into one niche. I work across roles, levels and geographies across the country. Right now I'm leading a head of development and construction search, and I've done a lot of asset management work at every level, along with investment, development, and debt roles. My clients range from family offices and private equity firms to institutional and smaller private developers.
What are your clients looking for? Have their goals shifted throughout the year?
Asset management has been consistently busy. The bigger shift has been happening in acquisitions and development. Two years ago, we weren't seeing much in that arena. Slowly but surely, those roles are coming back, and they're getting more senior. At the most senior level, they're often tied to a new venture, a new asset class, or succession planning. They aren't the majority of what we're working on, but the fact that we're seeing them again, above the analyst level, tells me people are doing deals. When there’s dealmaking, whether it's development or acquiring existing assets, it's good for the whole market.
There’s no rush, and it's been slow and steady. Without a major macroeconomic change, I don't see it turning into the frenzy of 2021, but activity is marching in the right direction.
The Fed has started raising rates and signaled more to come. How might that, and other macro dynamics, affect hiring and recruitment strategy?
Most of the people I talk to expected this increase, so I think many had already baked it into their strategy.
Macro shifts make firms ask whether they're still going to sell or buy as planned; they reconsider hold periods, capital deployment strategy and business plans for their assets. All of that affects who they need.
We've already seen this independently of rates. Developers in oversupplied markets are dealing with slower absorption, and many have decided to hold longer and let rents build before selling. A longer hold changes the business plan and returns associated with individual investments. Firms could look to grow their portfolio management teams to look at risk and business plans from a higher level.
Diversification also plays a role. A firm that wants to reduce its office exposure or move into industrial may need to bring on people with that expertise.
Transaction activity is a big question mark, but private credit has exploded and banks are back in the game. What are you seeing when it comes to deal flow?
We're seeing increased deal flow, but it's selective. It depends on asset class, geography and the deal itself.
Private credit is interesting to watch. A significant amount of capital was raised to fill holes in the capital stack left by banks, but over the past six months or so, bank lending has opened back up, making an already crowded debt market even more competitive. It is possible that the rate hike could tighten bank lending again and give private credit more room to deploy, but it is too soon to say.
For candidates, it's not a question of bank versus private credit. It's platform by platform. A well-established platform that's confident it can be competitive with its debt capital is going to be much more compelling than a newer entrant that may not know the space as well or may have unrealistic return expectations. Candidates need to understand how realistic a platform's plans are in today's market and how committed it is to making them work.
Have you noticed any marked differences in hiring and recruitment trends between New York and other national markets?
In New York, most development right now is focused on high-end condos and office-to-residential conversion, which only works for certain buildings. If that's where a firm is playing, there's activity. But I'm not seeing much ground-up market-rate multifamily. Nobody is really building speculative office, although the flight to Class A continues, and companies like JPMorgan are building for themselves.
Affordable and mixed-income residential development has slowed considerably since 421-a expired in New York, and a lot of what's being built is capped under 99 units. New York needs a policy that's more developer-friendly to drive meaningful construction.
New York developers have been investing in the Sun Belt and Florida for years, and that continues, but nobody is abandoning New York.
How should candidates adapt to this environment?
It depends on where you are. If you're in a good seat, it may be a waiting game. If you're a displaced developer, it could make sense to consider other U.S. markets. I recently worked with a candidate who had concerns about his firm's pipeline and ended up taking a role in Nashville.
It's also role-specific. New York is still the hub for capital, so for anyone in capital raising, investor relations or capital markets, relocation is less of a consideration.
Also, every candidate should be building AI fluency, but not relying on it entirely. Take what you can get from AI, and make it your own with your market knowledge and judgment. Things are changing quickly, so everyone should be experimenting with how it can make them more efficient and better at their jobs.
Is AI changing what clients look for in a candidate?
It's still evolving, and not every client is in the same place. Some now let candidates use AI on modeling tests or case studies, because they would use it on the job, and they want to see what candidates do with it. There's usually a conversation afterward about how the candidate approached the problem, so it becomes obvious if someone didn't put in their own work.
Other clients still have candidates take the modeling test in the office, using only Excel, because they want to confirm the fundamentals are strong. A year ago, I don't think any of my clients would have let candidates use AI during a test, so that's a real change. But there's no one-size-fits-all approach yet.
Looking ahead, which roles are in demand, and what's giving you optimism?
On the debt side, originations are in demand. Lenders want to put capital to work and grow what they're lending against. On the equity side, it's still all about asset management.
I'm optimistic. I expect a bit of a pop this fall, and I feel good about the start of 2027. I don't think there will be an explosion of hiring activity, but the market is in a much better place than it was a few years ago, and it's moving in the right direction.
For more Keller Augusta insights, visit the firm's LinkedIn or website.
